
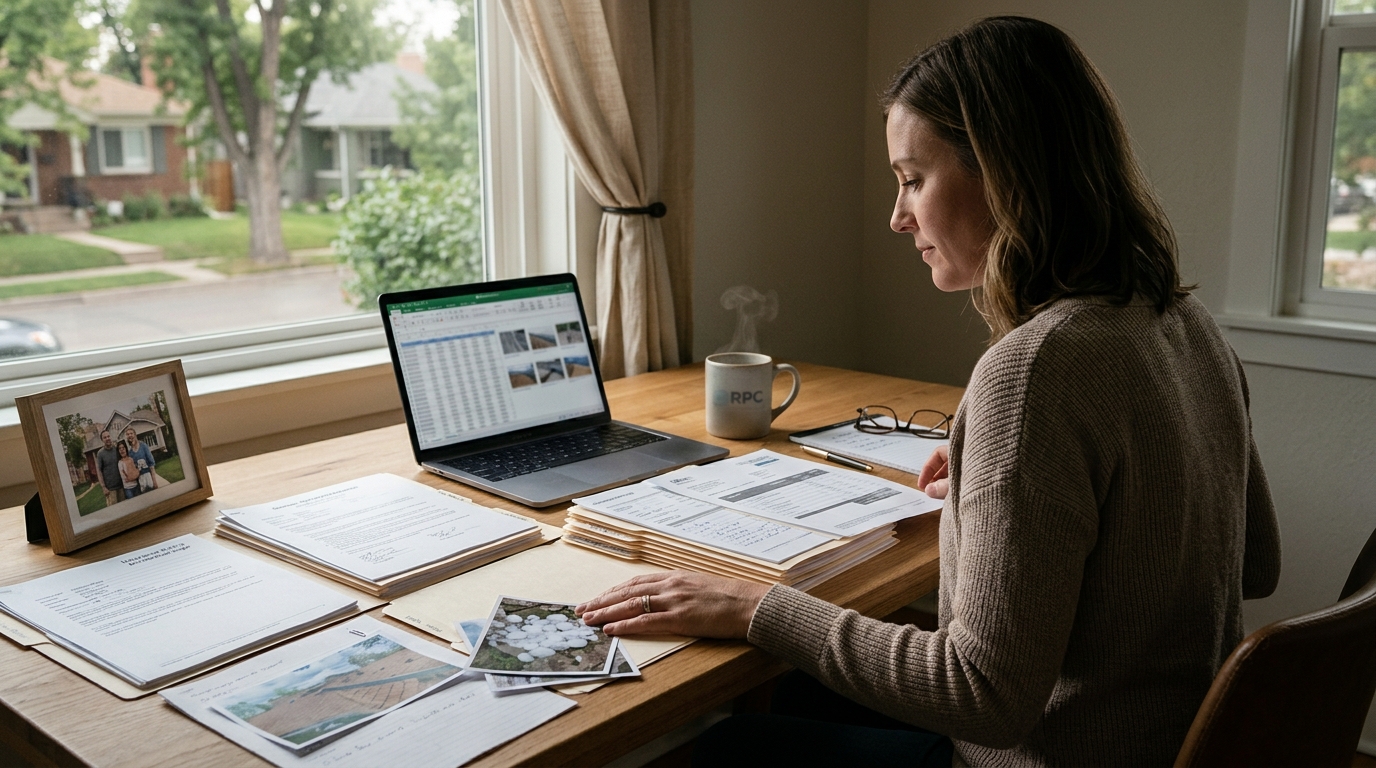
Filing a successful hail damage insurance claim requires a specific set of documents that prove the loss occurred and quantify the repair costs. You need your policy declaration page, a detailed damage inventory, professional repair estimates, and photographic evidence. Residential Property Contractors, LLC helps Denver homeowners organize these materials to ensure adjusters approve the full scope of necessary repairs without unnecessary delays or disputes.
Verifying Your Policy Coverage
Before gathering external evidence, you must confirm what your insurance policy actually covers. Policy coverage is the contractual agreement that defines the scope of protection, deductibles, and exclusions for your specific property. Hail damage is typically covered under the "dwelling" or "other structures" sections of a standard homeowners policy, but the specific terms vary by carrier.
Start by locating your policy declaration page. This document lists your coverage limits, deductible amount, and any endorsements you have purchased. If you have a windstorm or hail-specific endorsement, review it carefully. Some policies include a separate deductible for wind and hail events, which can be higher than your standard deductible. Understanding these financial thresholds helps you determine if the repair cost justifies filing a claim.
Check for any exclusions related to maintenance or wear and tear. Insurers often deny claims if they determine the damage resulted from a pre-existing condition rather than a specific weather event. If your roof is older than 20 years, the adjuster may scrutinize the claim more closely. Having your policy in hand allows you to anticipate these questions and prepare a defense based on the specific language of your contract.
Documenting Hail Damage Evidence
Visual evidence is the backbone of any property damage claim. Damage documentation is the process of recording the physical condition of your property before, during, and after the loss event. High-resolution photographs and videos provide the objective proof that hail struck your home and caused structural or cosmetic harm.
Photograph the damage from multiple angles. Include wide shots that show the location of the damage in relation to the whole house, as well as close-ups that reveal the specific impact points. For roofing, look for bruised shingles, cracked granules, or dented flashing. For siding, capture dents and scratches. If you have gutters or downspouts, photograph any visible dents. Do not edit or enhance these images. Adjusters rely on raw, unaltered media to verify the extent of the loss.
Create a written inventory of damaged items. List each affected component, such as "three shingles on the north slope" or "two dents on the west-facing gutter." Include the date of the storm and the date you discovered the damage. This timeline helps establish causality. If you have a smart home system or security cameras, export any footage from the day of the storm. This digital record can be powerful evidence if the adjuster questions the timing of the damage.
Securing Professional Repair Estimates
Insurance companies require a professional assessment to determine the cost of restoration. Repair estimates are detailed line-item breakdowns of the labor and materials required to return the property to its pre-loss condition. These documents must be prepared by licensed and insured contractors who understand local building codes and market rates.
Request a detailed scope of work from a qualified contractor. The estimate should not just list a total price. It must break down costs by category, such as demolition, materials, labor, and disposal. For example, a roof repair estimate should specify the number of shingles to be replaced, the type of underlayment, and the cost of flashing repairs. This level of detail allows the adjuster to verify that the pricing is reasonable and that no unnecessary work is included.
Residential Property Contractors, LLC provides comprehensive estimates that align with carrier requirements. We document concealed damage that may not be visible from the ground, such as moisture intrusion in the attic or structural framing issues. This thoroughness helps prevent disputes over the scope of work. A well-prepared estimate serves as the baseline for negotiations with the insurance company. It ensures that the final payout covers the actual cost of repairs, not just a superficial fix.
Submitting the Claim Package
Organizing your documents into a coherent package speeds up the claims process. Claim submission is the formal act of presenting your evidence to the insurance carrier for review. Most carriers have online portals where you can upload documents, but some may require physical copies or email submissions. Check your carrier's specific instructions before sending anything.
Compile your documents in a logical order. Start with a cover letter that summarizes the incident, the date of the storm, and the total estimated cost of repairs. Attach your policy declaration page, the damage inventory, and the photographic evidence. Finally, include the professional repair estimate. Label each file clearly, such as "Roof_Photos_North_Slope" or "Contractor_Estimate_2026." This organization makes it easier for the adjuster to review your claim and reduces the likelihood of requests for missing information.
Keep a copy of everything you submit. Save digital copies in a dedicated folder and print physical copies for your records. If you submit documents via email, request a read receipt or confirmation of delivery. This creates a paper trail that protects you if the carrier claims they never received your materials. A well-organized submission demonstrates professionalism and seriousness, which can influence the adjuster's initial assessment of your claim.
Managing Adjuster Communication
Communication with the insurance adjuster is a critical part of the claims process. Adjuster communication is the ongoing dialogue between the policyholder and the insurance representative who evaluates the loss. Clear, professional, and documented interactions help prevent misunderstandings and ensure that your concerns are addressed.
Keep a log of all conversations. Record the date, time, name of the adjuster, and a summary of what was discussed. If the adjuster makes a verbal promise or provides an estimate, follow up with an email to confirm the details in writing. This practice protects you if the adjuster later changes their position. It also helps you stay organized if you need to escalate the claim to a supervisor or file a complaint with the state insurance department.
Be prepared to answer questions about the damage and the repairs. The adjuster may ask why certain materials were chosen or why specific areas need replacement. Having your contractor available to answer technical questions can be helpful. Residential Property Contractors, LLC can attend the adjuster's inspection to explain the scope of work and the necessity of the repairs. This direct communication helps ensure that the adjuster fully understands the extent of the damage and the cost of restoration.
Key Takeaways
- Review your policy declaration page to understand coverage limits and deductibles before filing.
- Take high-resolution, unedited photos of all damage from multiple angles.
- Create a written inventory of damaged items with dates and locations.
- Obtain a detailed, line-item repair estimate from a licensed contractor.
- Organize your claim package with a cover letter and clearly labeled files.
- Keep a log of all communications with the insurance adjuster.
- Follow up on verbal agreements with written confirmation via email.
Frequently Asked Questions
What is the first document I should gather for a hail damage claim?
The first document you should gather is your insurance policy declaration page. This document confirms your coverage limits, deductible amount, and any specific endorsements related to wind or hail damage. It serves as the foundation for your claim and helps you understand your financial responsibility.
Do I need a contractor's estimate to file a claim?
Yes, most insurance companies require a professional repair estimate to determine the cost of restoration. This estimate should be detailed and include line items for labor, materials, and disposal. It helps the adjuster verify that the pricing is reasonable and that the scope of work is necessary.
How many photos should I include in my claim?
There is no specific number, but you should include enough photos to clearly show the extent of the damage. This typically includes wide shots of the affected areas and close-ups of specific impact points. Aim for clarity and completeness rather than quantity. Ensure all photos are unedited and high-resolution.
Can I file a claim if I don't have photos of the damage?
It is difficult to file a successful claim without photographic evidence. Photos are the primary way to prove that the damage occurred and to quantify its extent. If you do not have photos, you may need to rely on a professional inspection report, but this is less ideal. Always take photos as soon as you discover damage.
How long does it take to process a hail damage claim?
The processing time varies by carrier and the complexity of the claim. Simple claims may be processed in a few weeks, while complex claims with significant damage can take several months. Providing a complete and organized claim package can help speed up the process. Follow up with your adjuster if you do not receive a response within a reasonable timeframe.
What should I do if the adjuster denies my claim?
If your claim is denied, request a written explanation of the reason for the denial. Review your policy to see if the denial is consistent with the coverage terms. You can appeal the decision by providing additional evidence or requesting a re-inspection. If the appeal is unsuccessful, you may consider filing a complaint with your state's insurance department.
Next Steps for Denver Homeowners
Filing an insurance claim for hail damage requires preparation, documentation, and clear communication. By gathering the right paperwork and working with a qualified contractor, you can navigate the process with confidence. Residential Property Contractors, LLC is here to help you document your damage and prepare a strong claim package. To start your service request, today.